Why Oil Isn't Saving the Loonie: How Trade Tariffs and Rate Gaps Broke Canada's Petro-Currency Link
By Aaron C. Zhang, Senior Forex Market Analyst
For three decades, Canadian currency forecasting followed a straightforward formula: when crude oil rallied, the Canadian dollar followed. When West Texas Intermediate hovered between $80 and $100 per barrel, currency desks expected the loonie to trade between 78 and 82 cents US (1.22 to 1.28 USD/CAD). In late 2026, global crude sits near those levels, yet the Canadian dollar remains pinned down around 1.41. The traditional petro-currency link has broken down.
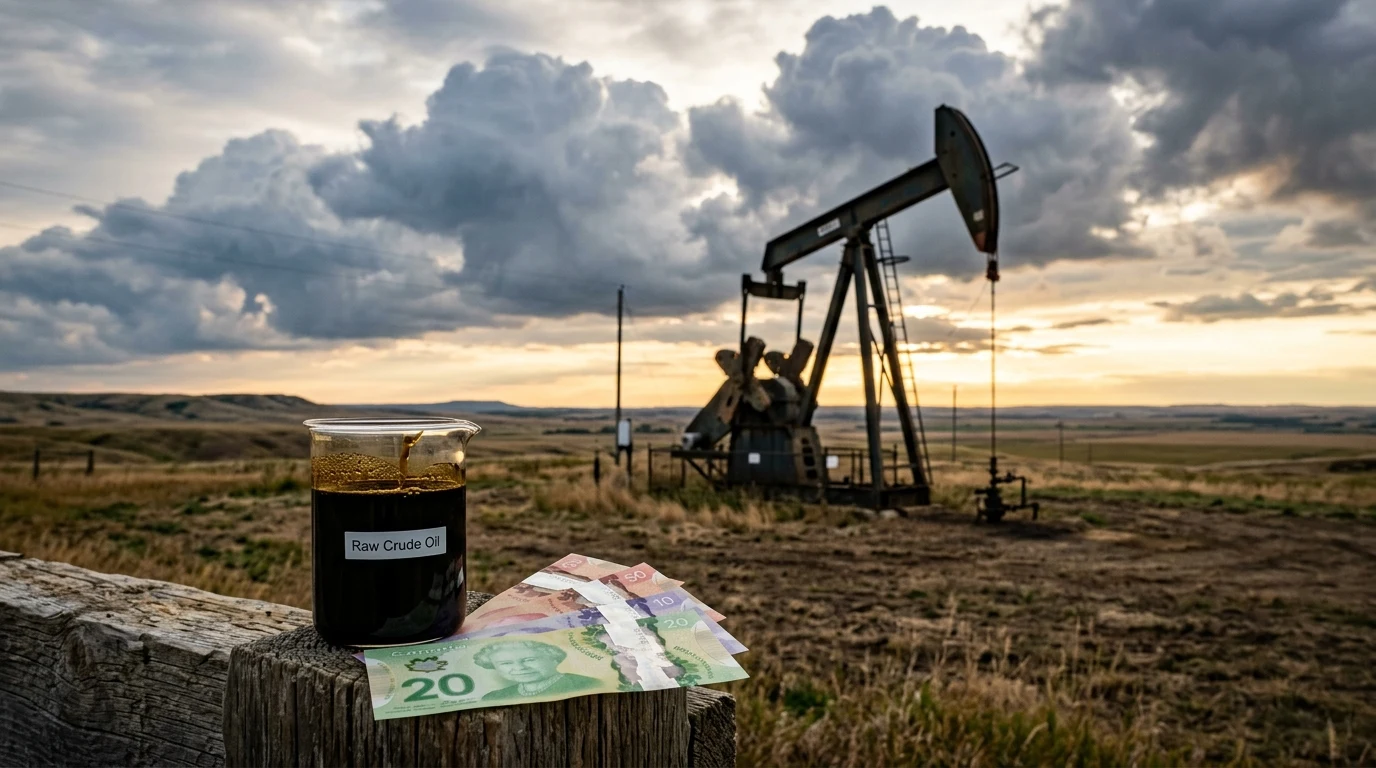
The historical relationship between crude oil and the loonie
Canada produces over 4.8 million barrels of crude oil per day, ranking as the fourth-largest producer in the world behind the United States, Saudi Arabia, and Russia. According to Statistics Canada, energy products account for more than 20 percent of Canada's gross export earnings.
Historically, this created a tight statistical correlation between crude prices and the value of the loonie. Between 2000 and 2014, the statistical correlation coefficient between WTI crude oil and the Canadian dollar exceeded 0.85. When international buyers purchased Canadian heavy crude (Western Canadian Select), they had to convert foreign currencies into Canadian dollars. That commercial conversion created continuous organic demand for the loonie.
The 2026 breakdown: what changed?
While energy export revenues remain substantial, three macroeconomic counter-currents have neutralized the oil dividend:
| Macro Factor | Historical Behavior | 2026 Reality | Net Effect on Loonie |
|---|---|---|---|
| Crude Oil Price | $80–$100 WTI pulled CAD to 1.25 USD/CAD | $85+ WTI coexists with 1.41 USD/CAD | Energy revenue absorbed by trade headwinds |
| Central Bank Rates | Bank of Canada matched or exceeded Fed rates | 150 bps gap in favor of US Fed rates | Capital exits CAD for higher US bond yields |
| Corporate Energy Cash | Reinvested into domestic megaprojects | Used for debt paydown and share buybacks | Reduced domestic capital spending in CAD |
| Trade Policy Stability | Tariff-free NAFTA/CUSMA access | 50% tariffs, annual CUSMA review deadlock | Severe risk discount on Canadian manufacturing |
1. The 150-basis-point interest rate gap
The single most powerful force counteracting oil revenue is the policy divergence between the Bank of Canada and the US Federal Reserve. In September 2026, the Bank of Canada held its overnight target rate at 2.25 percent. The central bank recognized that domestic consumer spending has slowed under high household debt loads, while US tariffs threaten industrial output.
In contrast, the US Federal Reserve has kept its policy rate higher, creating an interest rate spread of roughly 1.50 percent between the two countries. Institutional fund managers who hold billions in sovereign debt can earn significantly higher risk-free returns holding short-term US Treasury bills than Government of Canada bonds. That yield disparity generates steady capital flight out of Canadian dollars into US dollars, overpowering the daily inflow from oil sales.
2. How oil companies spend their cash windfalls
During the energy booms of 2005 to 2014, oil producers invested tens of billions of dollars directly into the Canadian ground. They hired engineering firms, built oil sands facilities in Alberta, and purchased industrial machinery from Ontario manufacturers. That domestic capital expenditure cycle created genuine employment demand and wage growth paid in Canadian currency.
In 2026, energy companies are operating under strict capital discipline. Instead of commissioning multi-year megaprojects, producers are directing free cash flow toward paying down US-dollar debt, distributing dividends to international shareholders, and buying back shares. Much of the oil revenue never converts into domestic economic activity; it remains parked in international corporate accounts.
3. Bilateral trade friction and the manufacturing discount
Canada is not only an energy exporter; it is a major producer of automotive assemblies, aerospace equipment, chemicals, steel, and agricultural products. While energy prices look healthy, the implementation of 50 percent tariffs on $20 billion of non-energy exports threatens the rest of the economy.
Foreign exchange markets evaluate the entire economy rather than an isolated commodity sector. When investors see trade disputes threatening automotive plants in Ontario and forestry operations in British Columbia, they apply a risk discount to the Canadian dollar. In our previous analysis of the loonie as a shock absorber, we showed how the currency falls to protect non-energy exporters from tariff costs, even when oil is trading at a premium.
What this means for Canadians exchanging currency
If you have been waiting for crude oil strength to push the Canadian dollar back toward 1.30 before exchanging funds, market fundamentals suggest that patience may not pay off in the near term:
- Do not rely on oil headlines as a timing indicator: Crude price spikes no longer translate into immediate loonie appreciation. Watching central bank interest rate meetings and CUSMA trade negotiations will give you a clearer read on currency direction.
- Protect against retail banking markups: When the wholesale exchange rate is already unfavorable at 1.41, paying an extra 3 to 4 percent to a retail bank teller magnifies your losses. You can monitor live wholesale rates on our Live Rate Board and compare spreads on our Bank Comparison Rates Page.
- Take advantage of fee-free currency exchange: Currency Mart waives all service fees on cash exchanges over $300 CAD. Whether you need US dollars for travel or business, physical branches in Toronto Downtown (PATH), Toronto North York, Winnipeg Downtown, and Winnipeg St. Vital offer competitive rates with cash in stock.
Frequently asked questions
Further reading on Canadian foreign exchange
- The Loonie as a Shock Absorber: How US-Canada Trade Talks Dictate the Canadian Dollar
- USD/CAD Pushes Past 1.41: Could Trade Tensions Drive the Canadian Dollar Toward 1.45?
- Canada's 2026 Economic Outlook: Interest Rates, Housing, and CAD Projections
- The Oil-Shock Comeback: Why the Loonie Defied Gravity During Global Energy Surges
- The True Cost of Converting CAD to USD: Big 5 Canadian Banks vs. Currency Mart
Stay in the know
Get live rate alerts and timely currency updates directly in your inbox.